


Introduction
Every financial system built over the last few centuries has run through intermediaries — banks that hold your money, brokers who execute your trades, insurers who process your claims. Decentralized finance, or DeFi, asks a genuinely disruptive question: what if those functions could run through code instead, without a company sitting in the middle collecting fees and controlling access? In this article, we’ll look at what DeFi actually replaces, how it works without a bank, and the real risks worth understanding before treating it as a straightforward alternative.
What DeFi Actually Replaces
Traditional finance relies on institutions to verify identity, hold funds safely, and enforce agreements. DeFi replaces those roles with smart contracts running on a blockchain: lending platforms that match borrowers and lenders directly, exchanges that swap one asset for another without a broker, and savings tools that pay interest without a bank account. The institution isn’t made more efficient — it’s removed from the transaction entirely.
How It Works Without a Bank
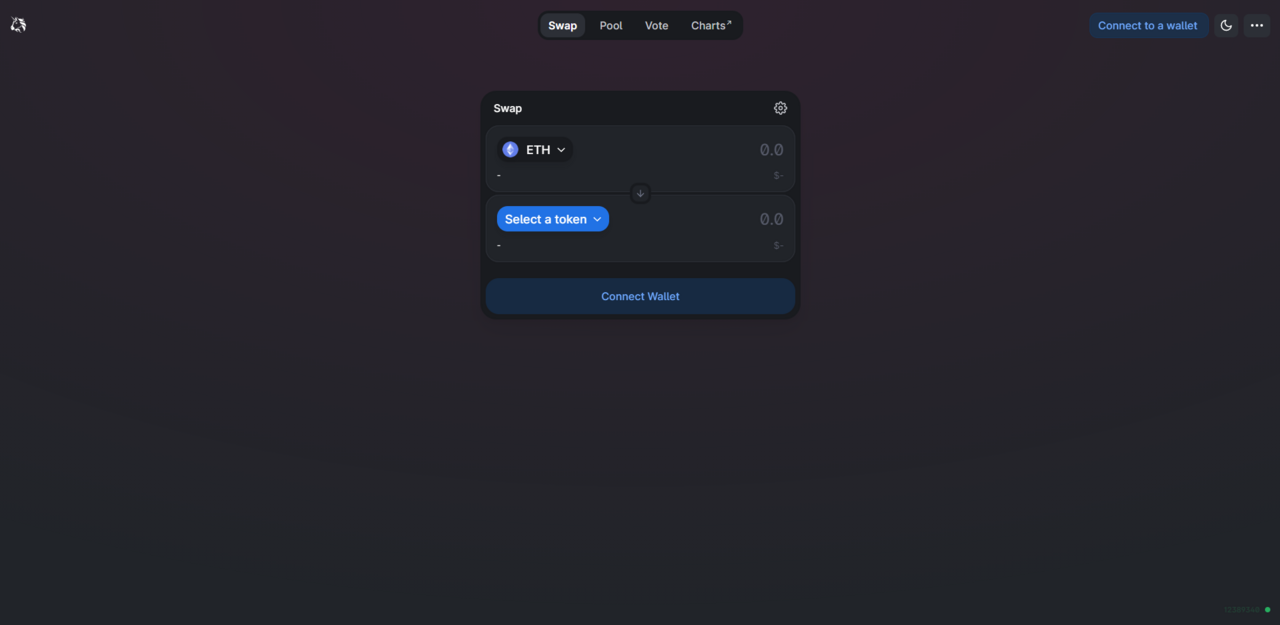
A decentralized exchange like the one shown above lets someone swap one cryptocurrency for another directly from their own digital wallet, with no account to open and no company holding their funds. The prices and available trades are set by automated pools of assets that anyone can contribute to, rather than a company’s own trading desk. Lending works similarly: rather than a bank deciding who qualifies for a loan, a smart contract matches lenders and borrowers automatically, based on collateral locked up as a guarantee.
The Appeal: Access and Yield
DeFi’s main draw is twofold: anyone with an internet connection can participate, regardless of whether a traditional bank would serve them, and lending or providing liquidity can earn a return that’s often set transparently by supply and demand rather than a bank’s own posted rate. That combination of access and yield is genuinely appealing, especially in regions where traditional banking is limited or unreliable.
The Risks Worth Taking Seriously
- No customer support, no chargebacks. A mistaken transaction or a lost private key is usually unrecoverable — there’s no bank to call.
- Smart contract bugs are real and costly. DeFi platforms have lost large sums to exploited code errors, sometimes irreversibly.
- Advertised yields can be unsustainable. Extremely high returns are often funded by new deposits rather than real underlying value — a pattern worth recognizing.
- Regulatory protection is thin or absent. The consumer protections that come standard with a bank account largely don’t exist here yet.
The Bottom Line
DeFi isn’t a scam and it isn’t a free lunch — it’s a genuinely different way of organizing financial services, with real advantages in access and transparency, and real risks that come from removing the safety nets institutions traditionally provide. Approaching it with the same caution you’d bring to any unregulated financial product is the sensible starting point.
ESPADMAG – A Place to: Mindset Achieve Greatness!
Photo credits: Helen Wells (CC BY 2.0); Hidden Lemon (CC0); nattanan (CC0); Jernej Furman (CC BY 2.0) — via Wikimedia Commons.
